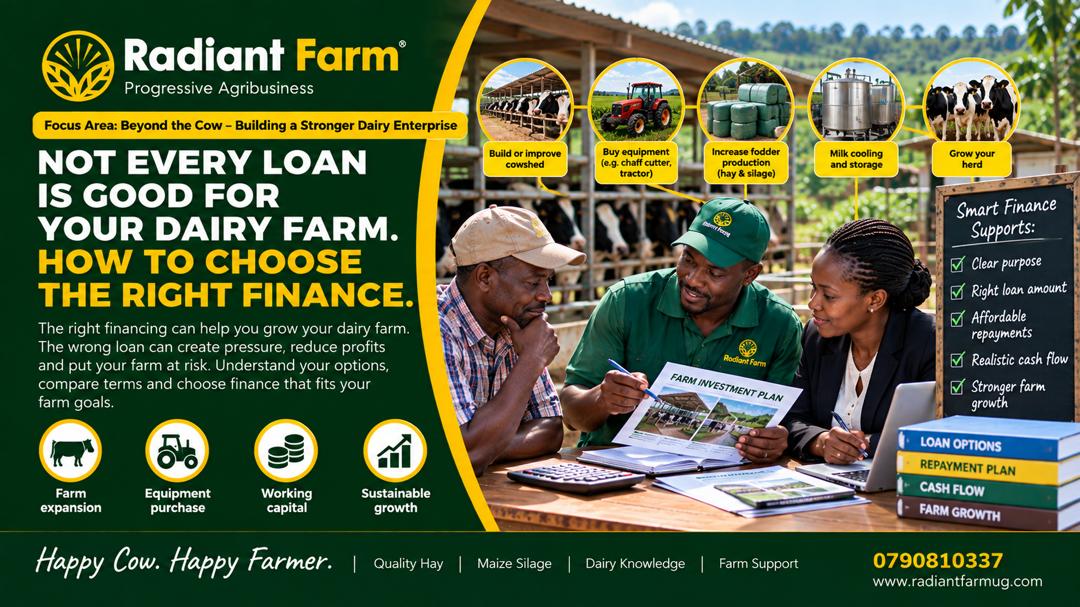
1. Start with the purpose, not the lender
Before approaching a bank, SACCO or another financier, be clear about what the money will do.
Financing a water system, milk cooler or productive animal is different from borrowing to cover recurring losses.
Ask yourself:
What will change on the farm because I borrowed this money?
If the answer is unclear, borrowing may only postpone the underlying problem.
2. Match the finance to the investment
Agriculture has seasons. Investments also take different lengths of time to generate returns.
A short-term facility may suit a short working-capital need. An investment that takes several years to pay back may require longer-term financing.
The repayment schedule should therefore make sense against the farm’s expected cash flow.
A useful investment financed badly can still become a bad decision.
3. Look beyond the advertised interest rate
The interest rate matters, but so do processing fees, insurance, collateral requirements, repayment frequency, penalties and other charges.
Farmers should ask for the total cost of the financing, not simply the headline rate.
Then ask another question:
What additional income or savings must this investment generate to comfortably cover those repayments?
4. Look for finance designed with agriculture in mind
Different sources of money serve different purposes. Depending on the opportunity, these may include commercial banks, SACCOs, agricultural lending programmes, development-finance institutions, equipment financing, farmer organisations or other sector-specific facilities.
The cheapest-looking money is not automatically the best.
Look for financing whose purpose, repayment structure and conditions fit the agricultural activity.
5. Borrow for productive capacity, not appearances
A new vehicle may look impressive. A reliable water system may not.
But which one improves the farm’s ability to produce, save costs, reach customers or manage risk?
Good farm investment often happens quietly, in water, infrastructure, equipment, genetics, storage, energy, market access or other productive systems.
Borrowing should strengthen the farm’s engine, not merely its appearance.
6. Sometimes the right financing decision is not to borrow
Can the investment be phased? Can farmers share equipment? Can a service be hired instead of buying the machine? Is there a partnership opportunity? Could retained farm income fund part of the investment?
Finance is a tool.
Debt is only one form of finance.
The Radiant Thought
A seed needs more than water to become a harvest. It needs the right conditions and enough time.
Capital is similar.
Money placed into the wrong investment, or demanded back before that investment can mature, can weaken rather than cultivate an enterprise.
One action this week
Write down one investment your dairy farm needs.
Beside it, answer four questions:
What will it cost? What additional income or savings should it create? How long before those benefits begin? What type of financing best matches that period?
Do that before asking, “Who will lend me the money?”
Radiant Farm Uganda Limited supports farmers with practical dairy knowledge, quality hay and maize silage as they build healthier, more productive and resilient dairy enterprises.
Need quality hay, maize silage or practical feeding support for your dairy herd? Contact Radiant Farm today on 0790810337 and let us help you improve productivity and farm returns.
Happy Cow. Happy Farmer.
📞Order forage from our website (click here) or from the nearby authorised dealer (click here to find out more)
😉 Call / WhatsApp to confirm your Hay or Maize silage ORDER NOW!
📩 Email: kampala@radiantfarmug.com
📍 Farm Location: Plot 5 Kitotolo Road, Nsangabwami Kikandwa, Mityana - Uganda.
By Oliver Namirimu,
Team Leader- Enterprise Management at Radiant Farm, specializing in sustainable farming practices and animal nutrition.
Please subscribe to our newsletter ( https://radiantfarmug.com/ ) for more updates from Radiant Farm Ug